“Did you forget to pay the loan this month?”
This is the message my mother sent me after 5 years during which €1,780 automatically left my account on the 1st of each month to pay off the family home near Lyon.
My name is Camille Durand, I’m 31 years old, and I work as a financial analyst. After my father’s death, my mother, Isabelle, kept the house and the old carpentry workshop where he worked. My sister, Élodie, had just opened a small clothing boutique. Between the commercial rent, inventory, and bills, she was constantly short of cash.
One Sunday, I found a bank reminder notice on the kitchen table. The mortgage was two months overdue. I paid without thinking. Then I set up a standing order.
At first, I thought I’d help for a few months. Five years later, I was still paying.
Added to that were electricity bills, a repair to the workshop door, and delivery costs for the shop. Meanwhile, my own savings to buy an apartment were progressing at a snail’s pace.
When I dared to say that I wanted to reduce my help, my mother simply replied:
— Family comes first.
Then, one Saturday in November, she asked me to retrieve an insurance file from my father’s binder.
Behind the shirt, I found a notarized document signed 2 months earlier.
My mother had given Élodie the bare ownership of the house and workshop, while retaining the usufruct. My name did not appear anywhere in the deed.
I read the same page three times. Then I photographed the documents and went home.
That same evening, I cancelled the automatic transfer.
Two weeks later, my mother wrote to me: “Did you forget to pay the loan this month?”
I replied with just one sentence:
“I will no longer pay for a house whose transfer you have already arranged without me.”
Four days later, my mother and sister rang my doorbell.
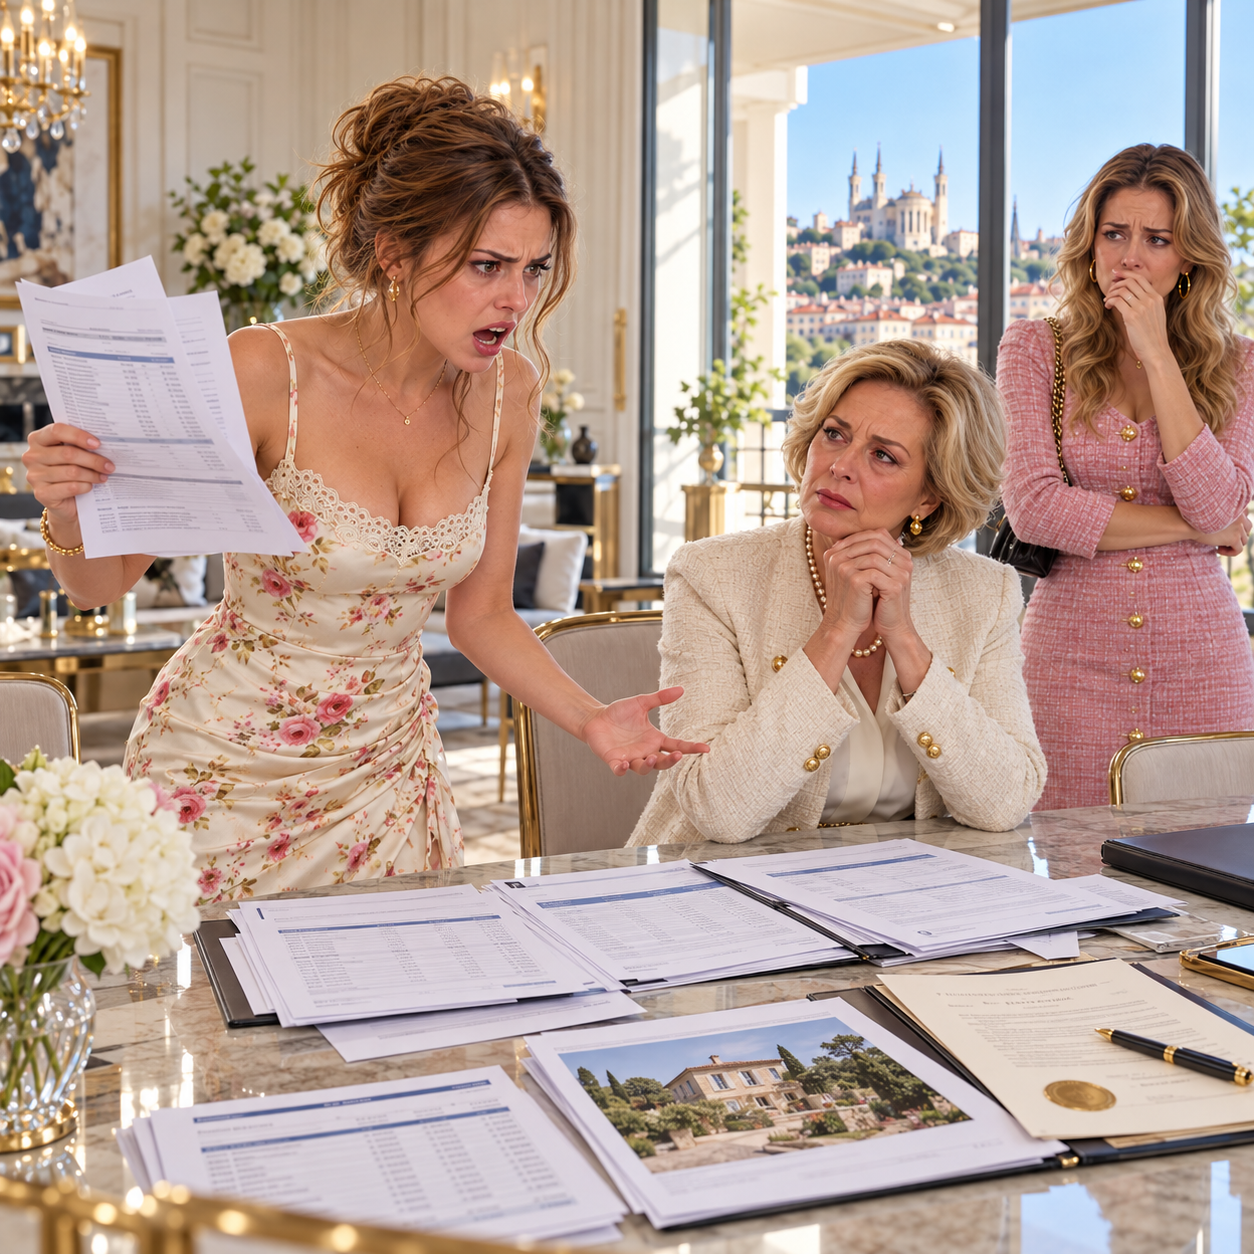
Élodie was holding a box of pastries. My mother, a bank file.
She placed it on my table and calmly said to me:
— You just need to sign as a co-borrower.
I opened the file.
On the last page, a small yellow sticker indicated exactly where I had to sign.
And my income was already entered.
At that moment, I understood that they had prepared much more than just a simple visit.
PART 2
I never gave my consent to be included in this file.
My mother explained that the bank refused to restructure the loan based solely on her salary. By adding my income, they could extend the loan term and reduce the monthly payment.
“You were already paying almost the same amount,” she said. “It doesn’t change anything for you.”
I watched Elodie.
— And the house?
She shrugged.
— Mom lives there. My stock is in the workshop. We’re just trying to save what belongs to the family.
I took out my phone and displayed the photos of the notarized document.
— No. You are trying to save an asset for which you have already received the bare ownership.
My mother’s face closed off.
She whispered that I was “mixing everything up”, that the donation had been made “to simplify the future” and that it didn’t change anything about the love she had for me.
But I wasn’t being asked for love.
I was being asked to take on a debt.
I refused to sign.
Two days later, a bank advisor, Mr. Lefèvre, called me. My number was listed in the file as a “prospective co-borrower.” I explained to him that I had not accepted any loan application.
He suggested I come to the already scheduled meeting, solely to hear the conditions.
I went there with two things: my transfer statements for the past 5 years and a copy of the deed of gift.
In the office, I asked 3 questions.
— If I sign, am I responsible for the loan even if I am not the owner?
“Yes,” replied the advisor. “You are obligated to repay according to the terms of the contract.”
— Does signing give me a share of the house?
— No. Lending and ownership are two different things.
My mother shifted in her chair.
I asked the last question:
— Since the bare ownership has already been given to my sister, what would I actually receive in exchange for this debt?
The advisor looked at the document, then at my mother.
— That’s not for the bank to answer. It’s a matter of inheritance that you should discuss with your notary.
Elodie sighed:
— Are you really going to let Mom lose the house over a paperwork issue?
I closed my file.
— No. I simply refuse to put my future in debt to finance someone else’s assets.
I thought the worst was behind me.
I was wrong.
Three weeks later, my mother sent me a photo of a letter from the bank.
The refinancing was refused.
Under the photo, she had written:
“Now you’ll see what you’ve done.”
PART 3
The next morning, I found 11 missed calls.
I didn’t call anyone back.
At 8:17 a.m., Elodie sent me a long message: the bank was demanding payment of overdue installments, penalties were increasing, and the shop was also at risk of being affected because part of its stock was occupying the workshop.
The last sentence said:
“If Mom has to sell, it will be because of you.”
I put my phone away.
For years, I had confused helping my family with becoming the silent funding mechanism for their decisions. At first, no one forced me. After my father’s death, I wanted to prevent my mother from losing the house and to preserve the workshop, his workbench, his tools, the lingering smell of wood in the walls.
But temporary aid had become an obligation that no one had ever discussed.
The following Wednesday, my mother asked me to come.